AI in auditing and tax: the use cases that work
Every accounting firm has sat through the same AI demo by now. The AI use cases that hold up in auditing and tax are unglamorous: testing the whole ledger instead of a sample, extracting data from invoices and receipts, and matching transactions during reconciliation. A chatbot giving tax advice is not one of them. Each use case still needs a human review step.
In the demo, a chatbot answers a tax question, everyone nods politely, and six months later nothing in the practice has changed.
That isn’t because AI doesn’t work in auditing and tax. It’s because the demos focus on the wrong thing. The useful work isn’t a chatbot. It’s the unglamorous middle of the job: extracting data from documents, matching transactions, and flagging anomalies.
Key takeaways
- AI is useful in practice for full-population audit testing, document extraction and reconciliation, with a human reviewing the output.
- UK Making Tax Digital for Income Tax started on 6 April 2026 for sole traders and landlords with qualifying income over £50,000, and extends to over £30,000 from April 2027 and over £20,000 from April 2028 (GOV.UK).
- In Kenya, business expenses not backed by an eTIMS invoice have not been tax-deductible since 1 January 2024, and KRA now validates income tax returns against eTIMS data (KRA).
- Never paste client data into a consumer chatbot, and never hand a client a general-purpose chatbot’s tax answer unchecked.
Can AI test a full ledger instead of a sample?
Yes, and this is where it earns its keep first. Traditional audit testing relies on sampling for a simple reason: no human can read a million ledger lines. Software can.
Running anomaly detection across an entire general ledger surfaces the entries a sample would statistically miss:
- postings made at weekends;
- round-number reversals sitting just under approval thresholds;
- a supplier who invoices exactly once a quarter for exactly the same amount.
The auditor still makes the judgement call. The difference is that they now make it with the full population in view, not a 5% sample and a hope that nothing important fell outside it.
Does AI document extraction actually work now?
The same shift from sampling to full coverage applies to paperwork. Turning invoices, bank statements, and receipts into structured data used to mean OCR software that broke on every new template. Modern AI models read documents the way a person does: they find the total, the VAT line, and the date regardless of layout.
For a tax practice, that changes the economics of the worst part of the job. When a client sends a shoebox of receipts as photos over WhatsApp, that’s now a categorised expense schedule rather than a lost weekend.
One caveat: extraction is probabilistic, not perfect. Anything that feeds into a filing needs a human review step. Firms that skip the review end up redoing the work, with less trust in the tools than they started with.
How are Making Tax Digital and eTIMS changing the picture?
Even firms with no appetite for this are being pushed towards it, because digitising is no longer optional in either of the markets we work in.
UK: Making Tax Digital for Income Tax
Making Tax Digital for Income Tax started on 6 April 2026 for sole traders and landlords with qualifying income over £50,000. It extends to those over £30,000 from 6 April 2027 and over £20,000 from 6 April 2028.
It requires digital records and quarterly updates sent through compatible software. Practices still running on annual spreadsheet handovers are already feeling that.
Kenya: eTIMS and KRA’s data matching
In Kenya, any business expense not supported by an eTIMS-generated invoice has not been tax-deductible since 1 January 2024, subject to a short list of statutory exceptions.
From 1 January 2026, KRA validates the income and expenses declared on income tax returns against eTIMS data, withholding tax records and customs import records. A one-off allowance covered some unsupported expenses on 2025 returns, but from the 2026 year of income every declared expense must be backed by a valid electronic tax invoice.
When the tax authority is running matching algorithms on your data, running none on your own side leaves you at a real disadvantage.
The pattern is the same in both countries: the regulator digitised first. Adopting AI on the practice side is largely about keeping pace with a counterparty that already automated.
How does AI help with reconciliation?
Bank-to-ledger matching, intercompany eliminations, supplier statement reconciliations. This is matching under messy conditions: truncated references, bundled payments, currency noise.
Rules-based tools handle the clean majority of transactions well. AI models are good at the messy remainder, like the “PAYPAL *JOHNSMI” reference a human would recognise in two seconds. Handing those cases to software is where the real hours come back, because the difficult cases were always where the time went.
The same document matching works outside accounting too: manufacturers use it to match purchase orders, delivery notes and supplier invoices.
Where does AI fall short in accounting?
Some honesty, because the sales pitches won’t offer any.
Tax advice from a general-purpose chatbot is a liability. Models give confident answers to questions that depend on jurisdiction, tax year, and facts they don’t have. Fine as a starting point for a professional who will verify everything. Dangerous as an answer handed straight to a client.
Confidentiality is not a footnote. Client financials pasted into a consumer chatbot may be retained and used for training. Check the provider’s data-use settings and business terms; they matter more than the model’s benchmark scores.
Professional judgement doesn’t automate. Going concern assessments, materiality, whether a director’s explanation actually adds up. The tools sharpen the evidence in front of the professional. They don’t replace the professional.
Where should a practice start with AI?
Not with a strategy deck. Pick one painful, repetitive, easily checkable process: expense categorisation, statement reconciliation, or invoice data entry. Automate that one thing, keep a human review step, and measure the hours before and after.
If the hours don’t move, stop. If they do, you’ve earned the right to automate the next thing.
That’s the whole method. It’s also roughly the AI automation we build for clients: small, verifiable automations that survive contact with real work, rather than platform rollouts that stall at the demo stage.
If you run a practice in Kenya or the UK and want a second opinion on which reconciliation or data-entry task AI would pay for first, book a free call with TekZuri and bring the process that eats the most hours.
Related posts
 · Yash Shah
AI in retail and e-commerce for small teams
Most of Amazon's AI playbook doesn't transfer to a ten-person retailer. These four pieces do, including the WhatsApp part everyone underestimates.
Read article→ · Yash Shah
AI use cases in manufacturing and supply chain
You don't need a data team to use AI in a factory. Practical wins in demand forecasting, quality inspection, maintenance, and the paperwork nobody talks about.
Read article→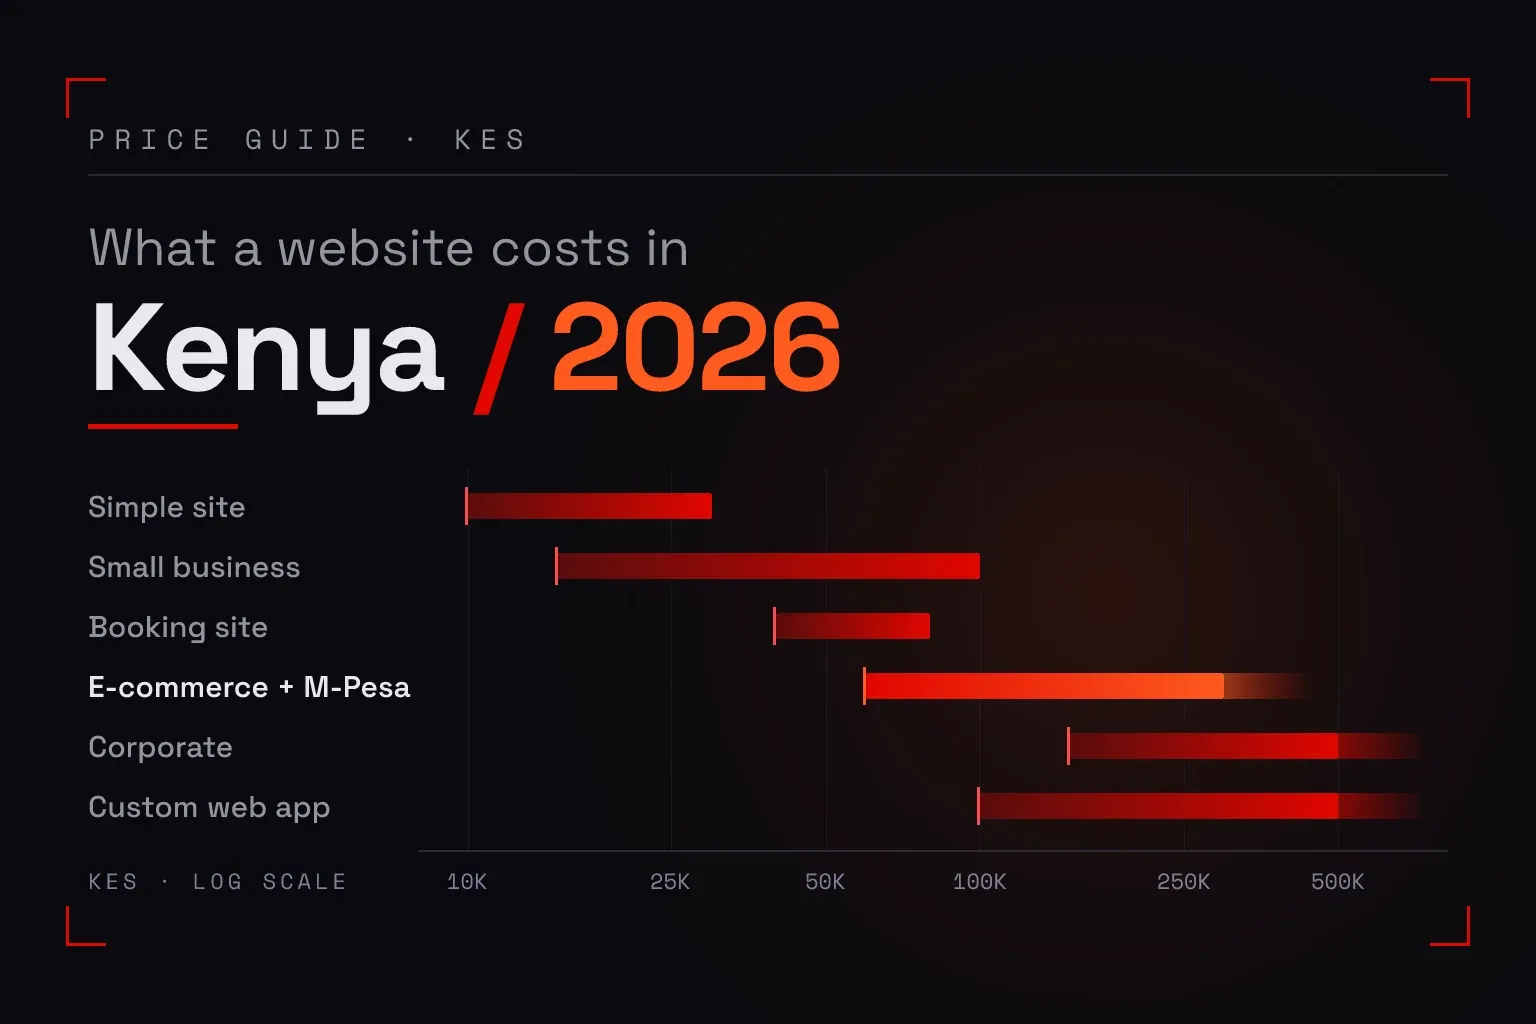 · Yash Shah
How much does a website cost in Kenya in 2026?
A website in Kenya costs about KES 10,000 to 100,000 for a simple or business site and KES 60,000 to 300,000+ for e-commerce with M-Pesa. 2026 guide.
Read article→